
Bank of America Projects High Dividend Potential for Brazil's Prio
An analyst report highlights Prio's cash-generation outlook, projecting up to $2.1 billion in potential annual dividends across 2027 and 2028.
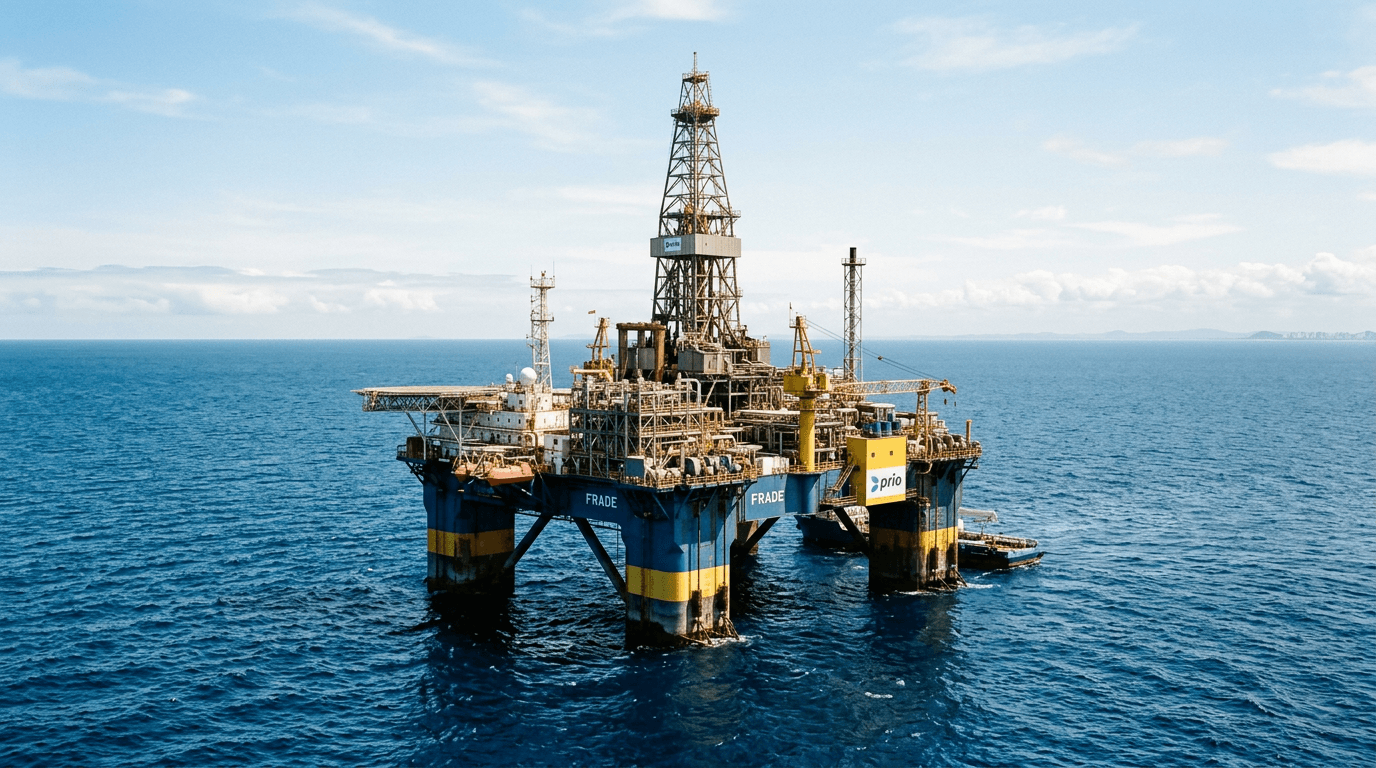
American retail investors holding Latin American small-cap funds may soon see a major shift in how one of their underlying holdings returns cash. A prominent independent oil producer in South America is on the verge of transitioning from a pure growth play into a significant dividend payer.
In a report released on October 14, 2026, Bank of America highlighted the cash-generation outlook for Brazilian independent oil producer Prio (PRIO3). The investment bank projected that the company could distribute between $2 billion and $2.1 billion in annual dividends across 2027 and 2028. Under these estimates, this would translate to a dividend yield of approximately 18% for each of those two years.
The projection is driven by higher Brent crude forecasts. In its October 14, 2026, report, Bank of America raised its 2026 average oil price estimate to $93 per barrel, up from $82, and its 2027 estimate to $80 per barrel, up from $70. These revised oil prices are expected to fuel substantial free cash flow to the firm's shareholders, estimated at $3.4 billion in 2027 and $2.8 billion in 2028.
Shifting From Growth to Payouts
Prio, formerly known as PetroRio, has built its reputation as one of the most successful value-creation stories in the Brazilian market by acquiring mature offshore oil fields, mainly in the Campos Basin, and driving down extraction costs. Historically, the company reinvested almost all its capital into buying these assets and expanding production rather than distributing cash.
According to Bank of America's analysis, the company's leverage is expected to remain highly conservative. Even under a stress-test scenario where Brent crude drops to $60 per barrel, the bank estimates Prio's net debt will not exceed one times its earnings before interest, taxes, depreciation, and amortization (EBITDA), leaving ample room for the projected payouts.
However, the actual distribution remains subject to board approval and the volatile path of global oil prices. Prio's management has historically favored share buybacks, and any sudden drop in commodity prices or a new large-scale acquisition could alter the company's capital allocation plans.
In your brokerage app
For investors looking to gain exposure to South American small caps, Prio is a major constituent of the iShares MSCI Brazil Small-Cap ETF (EWZS), a fund that tracks small-sized public companies in Brazil. While Prio does not have a direct US listing, retail investors can access its performance through this US-listed exchange-traded fund.