Why Brazil's 9.75% rate gap isn't translating into massive ETF returns
Brazil's central bank paused its rate cuts at 13.75%, leaving a massive yield gap with the US that acts as a shield against rising currency and political risks.

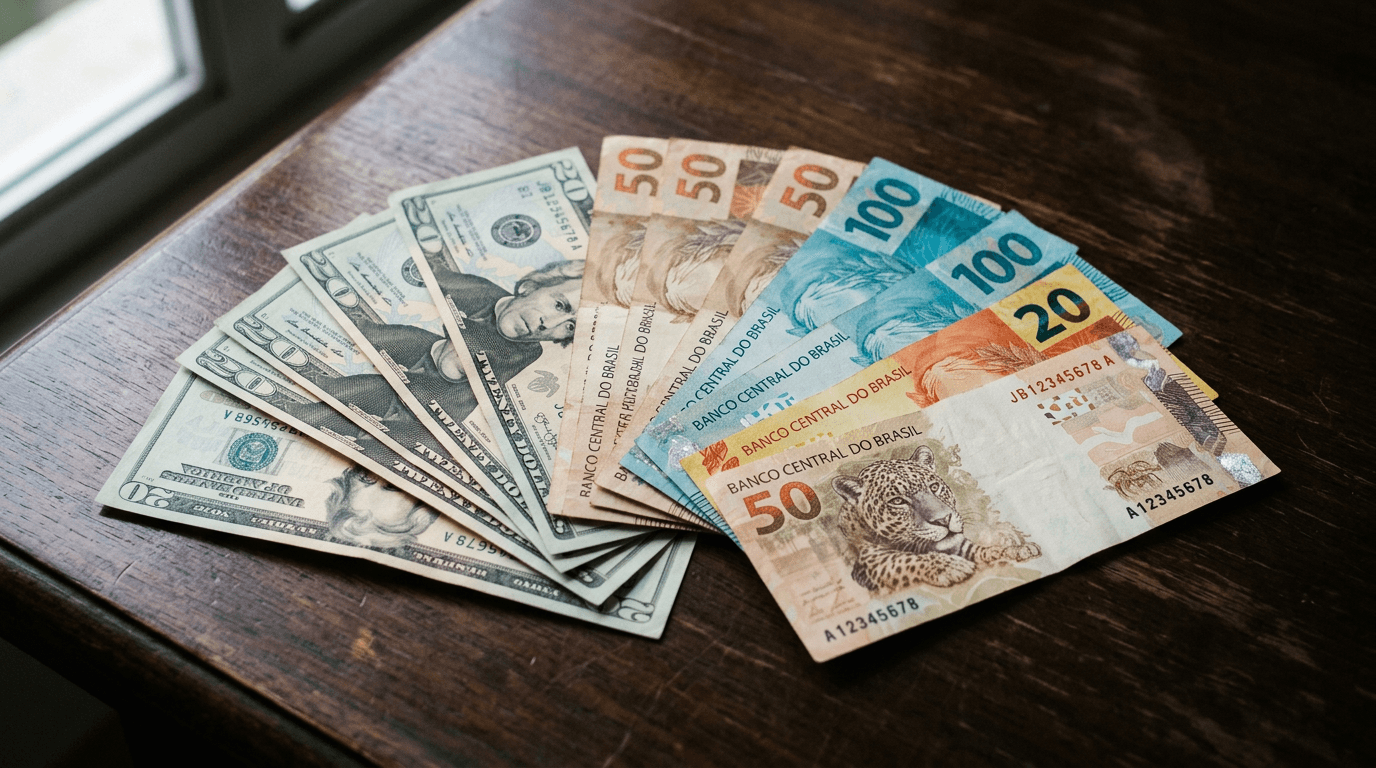
If you hold cash in a standard US brokerage account, your money is likely sweeping into a money market fund yielding around 4.0%. That rate, anchored by the Federal Reserve's upper target of 4.0% as of November 11, 2026, has drifted lower over the past year. For an American retail investor, a 4.0% return on risk-free US Treasuries is comfortable, but it sits in stark contrast to the massive yields offered just a short flight south.
In Brazil, the central bank is paying a benchmark interest rate of 13.75%. Known locally as the Selic target, this rate is set by the Banco Central do Brasil (BCB) and tracked under its official time-series code SGS 432. This leaves an enormous interest rate gap of exactly 9.75 percentage points between the US and Brazil—a spread that has remained completely unchanged over the past 30 days.
For global macro traders, this rate gap is the foundation of the "carry trade," where investors borrow dollars at low interest rates to buy high-yielding Brazilian government bonds. In a world of stable currencies, pocketing a 9.75% premium over US Treasuries would be an easy choice. However, for a retail investor holding a broad emerging markets fund, this massive yield gap has acted more like a defensive shield to offset currency losses rather than a wealth generator.
The reason is the volatile relationship between the brazil real vs usd. On November 4, 2026, the BCB's monetary policy committee, known as the Copom, voted unanimously to halt its rate-cutting cycle and hold the Selic at 13.75%. The central bank cited "significant uncertainties" following the October presidential election, which saw the re-election of President Luiz Inácio Lula da Silva. Local markets reacted with concern over Lula's upcoming fiscal plans, putting pressure on the brazil real to usd exchange rate.
When political risk rises, the currency depreciates. If the brazil real falls against the dollar by more than the 9.75% interest rate advantage, an American investor holding Brazilian debt actually loses money in dollar terms. This currency risk is why the massive yield gap has not triggered a major rally in Brazilian assets, as foreign investors demand a high premium to absorb the political and fiscal volatility in Latin America's largest economy.
In your brokerage app
If you own the iShares MSCI Brazil ETF, listed in New York, your portfolio is directly exposed to this interest rate dynamic. While the underlying Brazilian companies in the fund benefit from a stable currency, the fund's performance in US dollars is heavily dictated by whether the 13.75% Selic rate is high enough to defend the brazil real against a strong US dollar.