
Vale's Mixed Q2: Buyback Program Counters 35% Profit Drop and Rising Iron Ore Costs
Brazilian miner Vale reported a sharp decline in Q2 net profit, but a large new share buyback and higher-than-expected core earnings supported its B3 and NYSE shares.
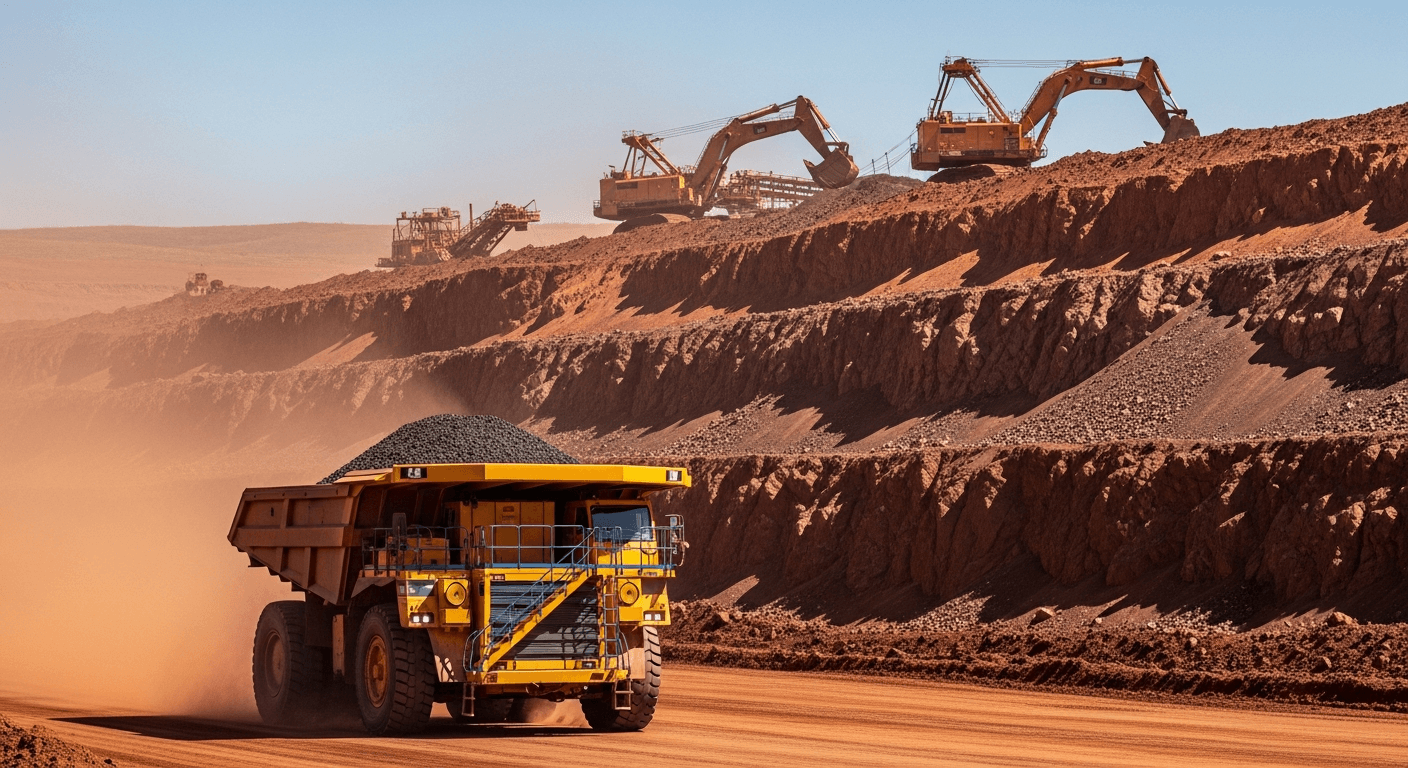
Vale S.A. (VALE3, NYSE: VALE), one of the world's largest Iron Ore producers, reported a net profit of $1.38 billion for the second quarter of 2026, marking a 35% year-over-year decline that was largely offset for investors by a major new capital allocation program. The results, published after the close of trading, present a mixed picture: while net income fell due to financial effects like derivatives and taxes, the company's core profitability, measured by adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) excluding non-recurring items, landed above analyst expectations at $4.07 billion. This financial nuance, combined with an announcement to return capital to shareholders, contributed to the Brazilian miner's strong performance on the B3, with the VALE3 ticker trading at 76.09, up 1.39% following the news. The broader Ibovespa today rose 1.88% to 177,158.86.
The main headwind for Vale's top line remains the rising cost of production. The company confirmed it is raising its 2026 C1 iron ore cash cost guidance from a previous range of US$20-21.5 per ton to a new range of US$22.5-23.5 per ton. This increase is a direct result of macroeconomic pressures, particularly the strengthening of the Brazilian Real against the U.S. dollar, which increases local currency costs when translated into the reporting currency, and higher global oil prices. The underlying operational strength in Iron Ore, however, was evident as the miner achieved its highest second-quarter production since 2018.
To counter the profit dip and address the cost visibility issues, the Vale board approved a significant expansion of its shareholder return program, a classic move to place a floor under the stock price. The company announced a new share buyback program authorized to repurchase up to 100 million common shares, including their respective American Depositary Receipts (ADRs), over the next 18 months. This figure represents approximately 2.3% of the company's total shares outstanding, signaling management's confidence in the company's valuation despite current market pressures. The company also announced a payment of $1.7 billion to shareholders through dividends and interest on equity.
For investors tracking the sector or holding the Brazil ETF (EWZ), the key watch point is the trajectory of the C1 cash cost. Vale's actual C1 cost hit US$23.6 per ton in Q1 2026, already above the newly established guidance range. The company's ability to pull costs down from the Q1 spike and remain within its new, higher guidance will be critical in Q3 to maintain margins and ensure that the positive market reaction, driven by the buyback and core earnings beat, is sustained over the long term.
Related coverage
Markets · PRO
Brazil Finance Ministry Cuts 2026 GDP Forecast to 2.0% on Drag From High Selic Rate
Published
Markets
Brazil's Election Divide Crystallizes Over Fiscal Rules, Lula Rejects PIX Privatization
Published
Markets · PRO
Petrobras to Drill Three More Equatorial Margin Wells After Securing IBAMA Approval
Published