
Emerging market funds face test as Brazil's post-election rally cools
A post-election surge in Brazilian equities has global asset managers re-evaluating Latin America's largest economy amid shifting political risks and historical valuation gaps.
American retail investors holding broad international or emerging market funds in their retirement portfolios may soon see their performance tied to a dramatic shift in South America. A post-election stock rally in Brazil has prompted local financial institutions to adjust their long-term models, forcing global asset managers to re-evaluate their exposure to Latin America’s largest economy.
Following a major political shift in the first round of Brazil's presidential election, the digital investment bank Banco Inter revised its projection for the benchmark Ibovespa index, as reported by local financial outlets on October 18, 2026. The index had surged 8.8% in local currency—and roughly 12% in US dollars—during the week following the October 2026 first-round vote, marking the largest post-election weekly gain since 1994.
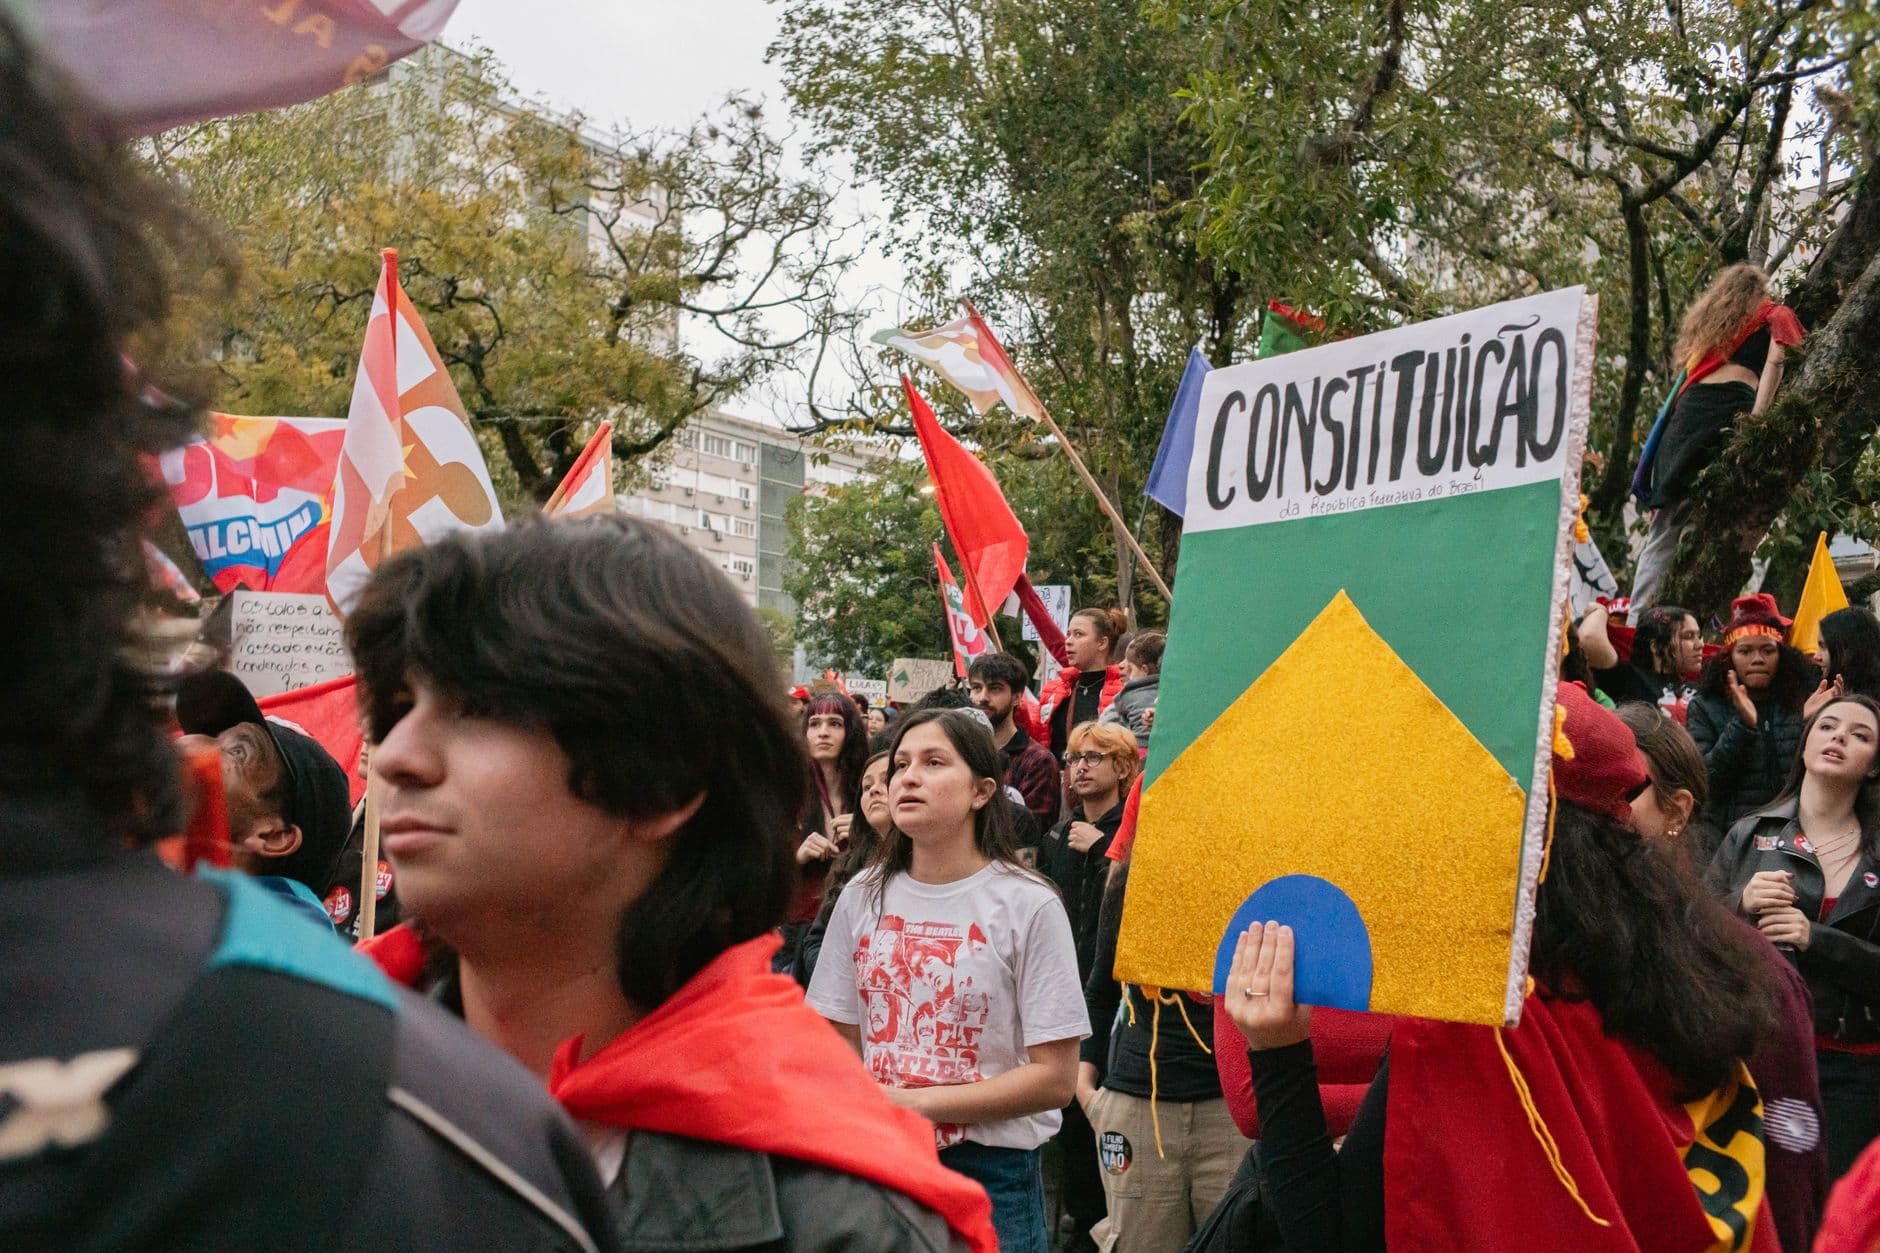
The sudden market optimism stems from a changing political landscape that directly impacts state-controlled enterprises. In the first-round presidential vote, conservative challenger Flávio Bolsonaro of the Liberal Party finished ahead of the incumbent leftist President Luiz Inácio Lula da Silva. For global investors, the electoral shift has introduced a powerful mechanism: the rising probability of market-friendly reforms and potential privatizations of massive state entities, such as the state-run oil giant Petrobras and the lender Banco do Brasil. While President Lula's administration has favored state-led development, the strong showing by the opposition has led Wall Street analysts to price in a lower political risk premium.
Cheap Valuations Despite the Surge
Despite the rapid post-election run-up, analysts argue that Brazilian equities remain historically cheap compared to their long-term averages. According to an October 18, 2026 report by Banco Inter analyst Rafael Winalda, the Ibovespa is currently trading at just over 10 times projected earnings. This is notably below its long-term historical average of 11 times earnings, and far cheaper than many other major emerging market peers.
The investment thesis does not rely on an economic miracle, but rather on a simple reduction of the "Brazil discount" that has depressed local stock prices for years. Between 2024 and early 2026, severe fiscal concerns and high domestic interest rates dragged the market down to multiples as low as 7 to 8 times earnings. Consequently, local analysts view the current momentum as a healthy valuation recovery rather than speculative overheating.
However, this bullish outlook faces a critical test in the upcoming second-round presidential run-off. If the political momentum shifts back or if post-election fiscal policies fail to address Brazil's structural deficit, the market's newly found optimism could quickly evaporate, exposing foreign investors to currency volatility and sudden capital outflows.
In your brokerage app
For retail investors tracking Latin American market exposure, the largest corporate players in the region are accessible via major US brokerages. This includes neobank operator Nu Holdings, which is listed in New York and serves as a major component of broad emerging market funds, alongside natural resource exporter Vale and state-controlled energy firm Petrobras.