
Analysts Flag PETR4, Multiplan (MULT3) as Top Q2 Earnings Plays Despite Ibovespa Dip
Analysts highlight Petrobras (PETR4) and Multiplan (MULT3) for potential Q2 earnings strength, driven by refining margins and strong sales despite market weakness.
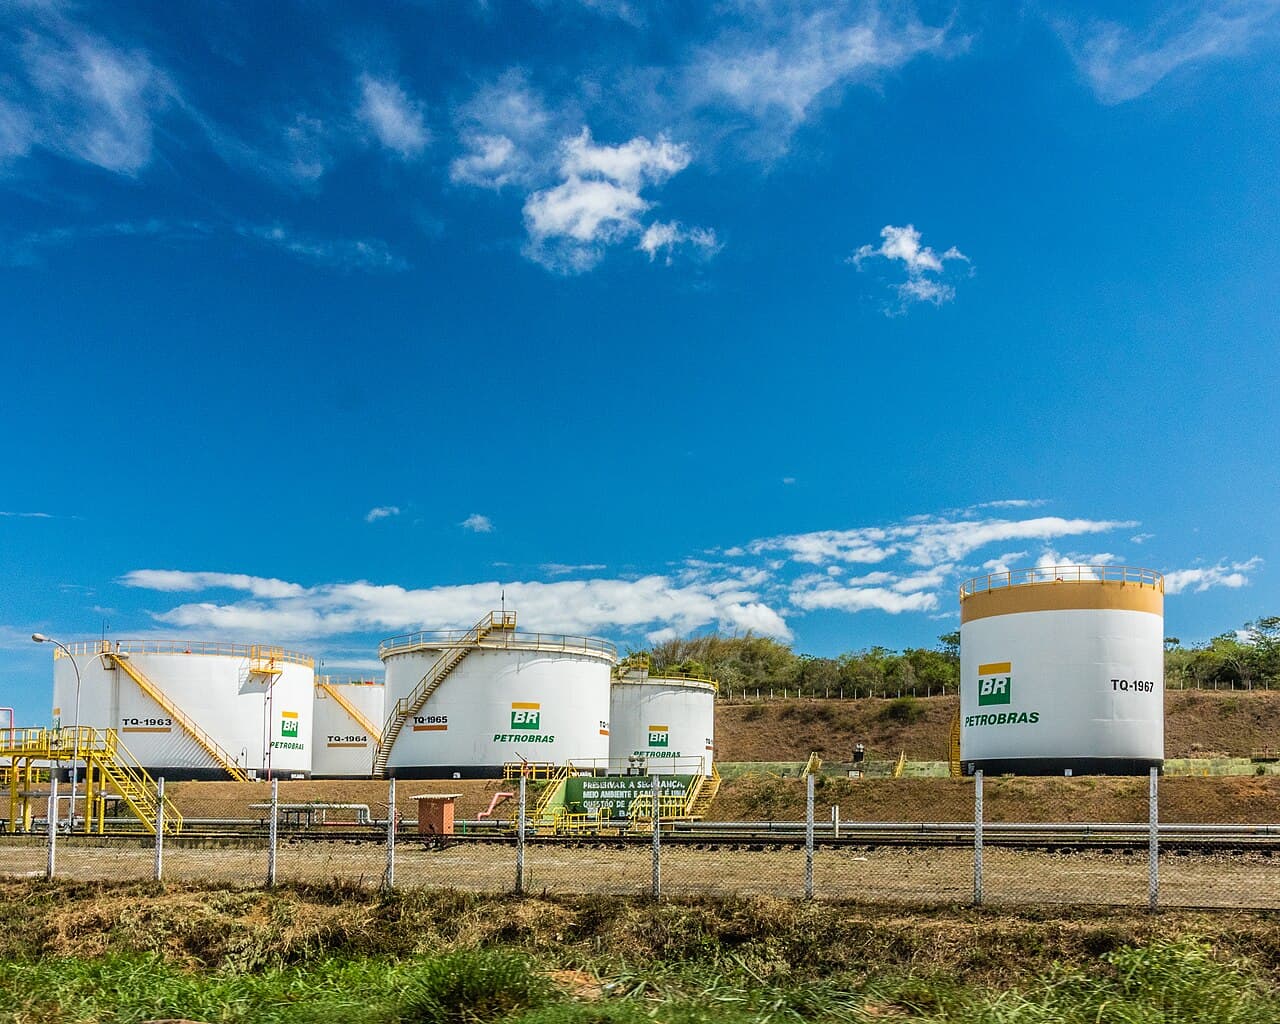
Despite a weak start to the week for the broader Brazil stock market, with the Ibovespa index falling 1.52% to 174,041.95, two major names are being highlighted by analysts for potential strength in the upcoming second-quarter (Q2) 2026 earnings season: state-run oil company Petrobras (PETR4) and shopping center operator Multiplan (MULT3). Research reports from BTG Pactual and Santander point to company-specific tailwinds that are expected to translate into strong financial results, contrasting with the negative momentum seen in today’s trade, where PETR4 common shares fell 1.72% to R$42.21.
For Petrobras, BTG Pactual has reinforced its optimistic view on PETR4, citing the company's strong position to capitalize on persistent geopolitical risk and the resulting high crude oil prices. The core mechanism driving the expected earnings strength lies in the oil giant’s refining segment. BTG Pactual analysts project an increase in refining margins, noting that approximately 70% of Petrobras’s crude production is used as feedstock in its own refining facilities. This margin expansion is amplified by a structural diesel supply deficit, caused by a reduction in global refining capacity and restrictions on Russian exports, a scenario the bank believes will keep margins high even if crude prices moderate.
In the retail and real estate sector, Santander singled out Multiplan (MULT3) as a top pick among shopping center operators, reiterating its positive outlook. The bank forecasts another solid quarter for the company, driven by two key factors. First, Multiplan is expected to benefit from robust sales volume across its portfolio of high-quality malls, reflecting resilience in consumer spending in its target demographics. Second, the Q2 results are anticipated to be boosted by non-recurring tax credits, which will provide an additional lift to the bottom line.
The divergence between the general market weakness and the specific bullish forecasts for these two Brazilian blue chips suggests that investors are increasingly focused on individual company fundamentals ahead of the core earnings period. For investors tracking these names, the release of the official Q2 2026 results will be the critical next data point, testing whether the projected tailwinds—namely, sustained oil and refining strength for PETR4 and sales volume combined with tax credits for MULT3—materialize into the outperformance analysts are forecasting.
Related coverage
Markets · PRO
Brazil Finance Ministry Cuts 2026 GDP Forecast to 2.0% on Drag From High Selic Rate
Published
Markets
Brazil's Election Divide Crystallizes Over Fiscal Rules, Lula Rejects PIX Privatization
Published
Markets · PRO
Petrobras to Drill Three More Equatorial Margin Wells After Securing IBAMA Approval
Published