Brazil’s Central Bank Rate Cut Spurs Rotation Toward Domestic-Facing Stocks
The fifth consecutive cut to Brazil’s benchmark Selic interest rate, now at 13.75%, is driving a rotation of capital out of fixed income and into equity sectors sensitive to lower credit costs, such as retail and civil construction.
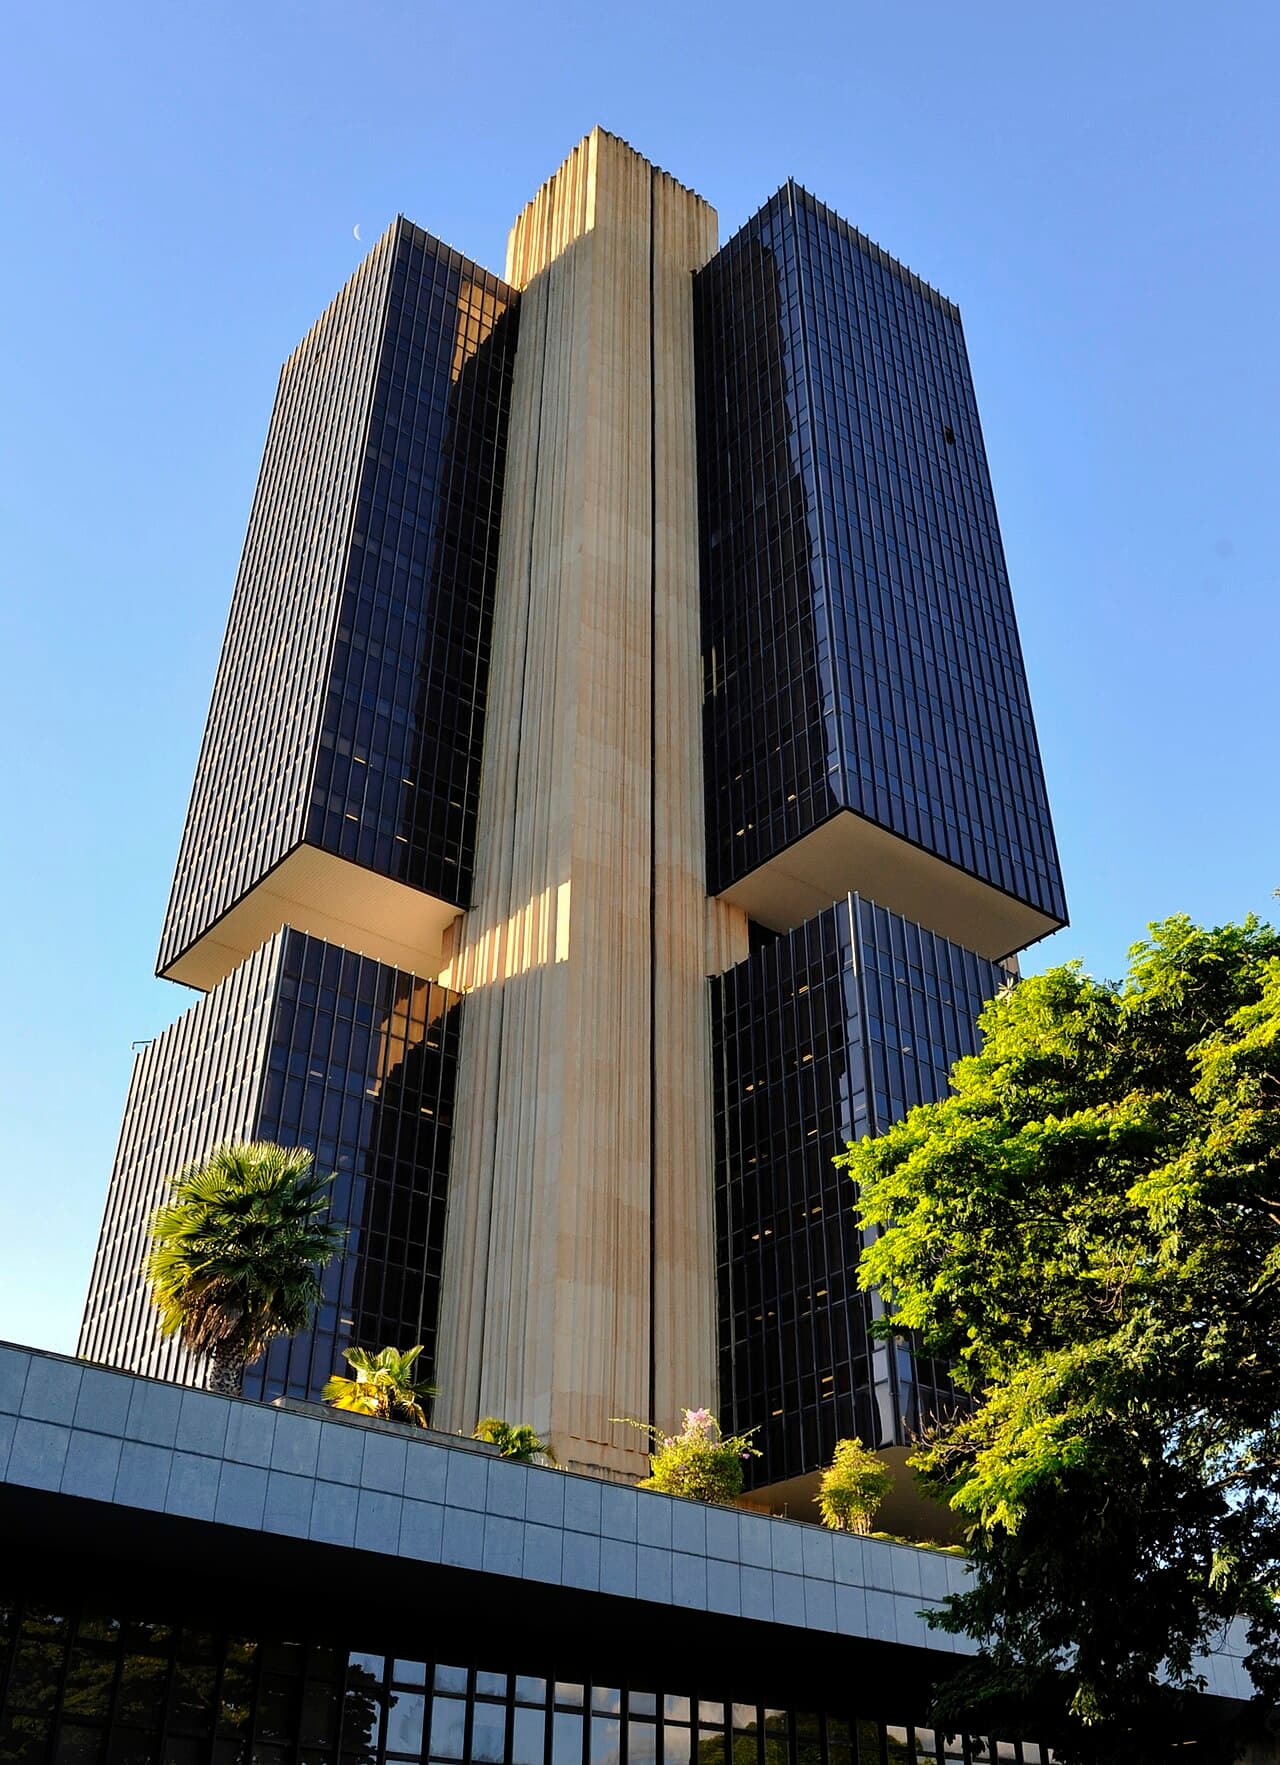
Brazil's central bank, the Banco Central do Brasil, has continued its monetary easing cycle, lowering the benchmark Selic interest rate for the fifth consecutive time. As of the September 16 meeting, the rate now stands at 13.75% per year.
The move by the Monetary Policy Committee (Copom)—Brazil’s equivalent of the U.S. Federal Reserve’s FOMC—is widely anticipated to trigger a shift of capital from high-yield fixed income investments back into domestically focused equities.
Analysts are now highlighting sectors acutely sensitive to the cost of credit and domestic economic activity as the primary beneficiaries of this easing.
The logic is a classic rotation: as the high fixed returns on government bonds and other fixed-income instruments fall, the equity market becomes a more attractive proposition. This is especially true for sectors that were crippled by the historically high rates that previously kept the Selic as high as 15%.
This rotation creates an opportunity for a "catch-up" trade as credit costs slowly decline across the Brazilian economy.
The two most frequently cited sectors poised for a boost are Civil Construction and Retail. The high Selic rate had previously constrained household finances and made mortgages and consumer credit prohibitively expensive.
A lower rate is expected to reduce financing costs for builders and, crucially, make real estate credit more accessible to consumers, spurring demand for new homes. Similarly, the retail sector stands to benefit directly from an expected increase in consumer demand as installment plans become cheaper and households gain more budget room.
Beyond established large-cap companies, domestic analysts are focused on the expected outperformance of Brazil Small Caps. These smaller companies typically have higher operating leverage and a greater reliance on bank credit and domestic demand than their commodity-exporting large-cap counterparts.
For small and medium-sized enterprises, many of which carry high levels of debt due to Brazil's historically high cost of capital, lower funding costs could lead to balance sheet repair and a significant boost to earnings.
However, this enthusiasm is tempered by a crucial technical detail. While the overnight Selic rate has fallen, the longer end of Brazil’s yield curve has not dropped with the same conviction.
These two-to-five-year interest rates govern long-term corporate loans and investment decisions. For many smaller businesses, the cost of long-term capital remains painfully high, suggesting the full benefits of the Central Bank's cuts may not be reflected in corporate earnings for several more quarters.
The next concrete event to watch will be the release of the Copom meeting minutes. This release will provide foreign investors with a clearer signal on the committee’s assessment of inflation risks and their forward guidance for the pace and magnitude of future rate cuts.
What it touches
The market rotation favors domestic-facing companies over the commodity giants that dominate Brazil's large-cap indices. This shift applies directly to companies in the real estate, homebuilding, construction, and consumer discretionary sectors, as well as the exchange-traded funds (ETFs) and indices that track the Brazilian small-cap universe.
Related coverage
Investing
Brazil’s Central Bank Cuts Selic Rate to 13.75%, Boosting Retail and Construction Prospects
Published
Investing
Brazil’s 13.75% Selic Rate Holds Down Consumer Credit, Caps Savings Returns
Published
Investing
Dutch-Owned iFood Commits Record R$24 Billion Investment to Boost AI and Fintech in Brazil
Published