Bradesco Profit Rises 14.6% as Rising Bad Loans Highlight Credit Risk
Banco Bradesco reported a 14.6% rise in Q3 2026 recurring net profit to R$7.1 billion, but rising delinquency rates underscore ongoing credit pressures.
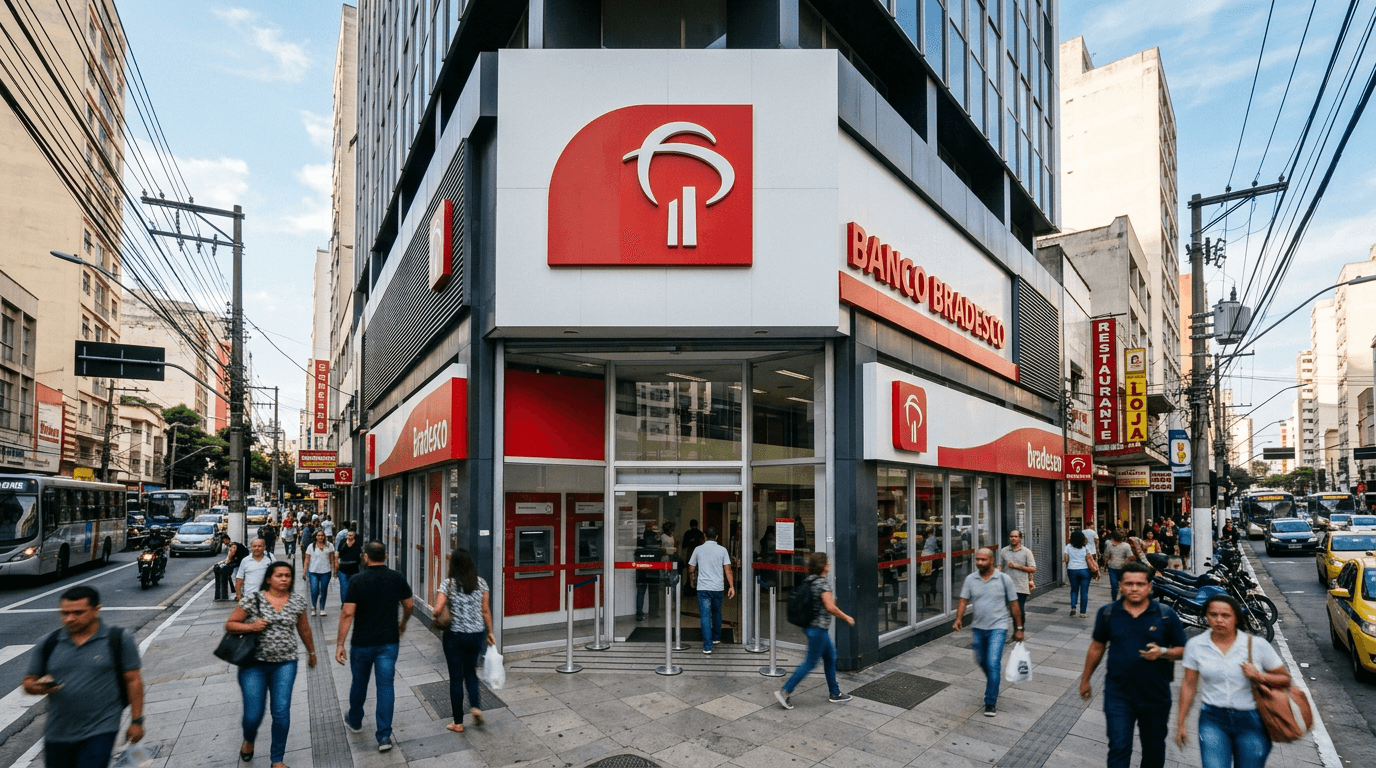
A sharp rise in loan-loss provisions is tempering the positive impact of double-digit profit growth at one of Brazil's largest financial institutions. According to the bank's Q3 2026 earnings release published on October 22, 2026, Banco Bradesco S.A. reported a recurring net income of R$7.1 billion (approximately $1.41 billion). This bottom-line figure represents a 14.6% increase compared to the same period in 2025.
The profit expansion was primarily supported by a 14.2% year-over-year increase in net interest income, which reached R$21.4 billion, alongside disciplined cost controls and an 11.1% expansion of its total loan portfolio to R$1.15 trillion. However, the bank's aggressive push to expand its credit portfolio has come with a visible rise in credit risk.
Bradesco's expanded loan-loss provision expenses jumped 24.3% year-over-year to R$10.6 billion for the quarter ending September 30, 2026. This sharp rise in provisions reflects deteriorating credit quality, particularly among small businesses and loans backed by government-guaranteed programs.
Rising Delinquencies Under High Interest Rates
The underlying pressure on Brazilian borrowers is clearly visible in the bank's delinquency metrics. Bradesco reported that its over-90-day non-performing loan (NPL) ratio rose to 4.6% in the third quarter of 2026, up from 4.1% a year earlier and 4.3% in the preceding quarter. Chief Executive Officer Marcelo de Araujo Noronha noted during the earnings call on October 23, 2026, that a challenging macroeconomic environment has forced the bank to maintain a more selective risk appetite.
To counter these headwinds, Bradesco's management has shifted its focus toward lower-risk, collateral-backed credit lines, such as payroll loans, vehicle financing, and mortgages. At the same time, the bank has actively scaled back its exposure to unsecured personal loans and high-risk small-business segments. While this defensive posture helps protect the bank's balance sheet, the transition to lower-yielding corporate and collateralized loans has put downward pressure on its net interest margins.
Political and monetary policy developments continue to influence the Brazilian financial sector. The Central Bank of Brazil has kept its benchmark Selic interest rate elevated to combat inflation, a policy that directly increases the cost of debt service for retail and corporate borrowers alike. For global market participants, a key uncertainty is whether Bradesco's ongoing digital restructuring and selective lending strategy can outpace these systemic credit pressures over the long term.
In your brokerage app
Banco Bradesco S.A. is listed in New York as an American Depositary Receipt (ADR) under the ticker BBD. The company is also a major holding in broad emerging market and country-specific exchange-traded funds, such as the iShares MSCI Brazil ETF.