
Why the 9.75-Point Rate Gap Between the Fed and Brazil Matters
The yield premium between Brazil's Selic rate and the U.S. federal funds rate sits at 9.75 percentage points, driving the carry trade and foreign exchange risk.
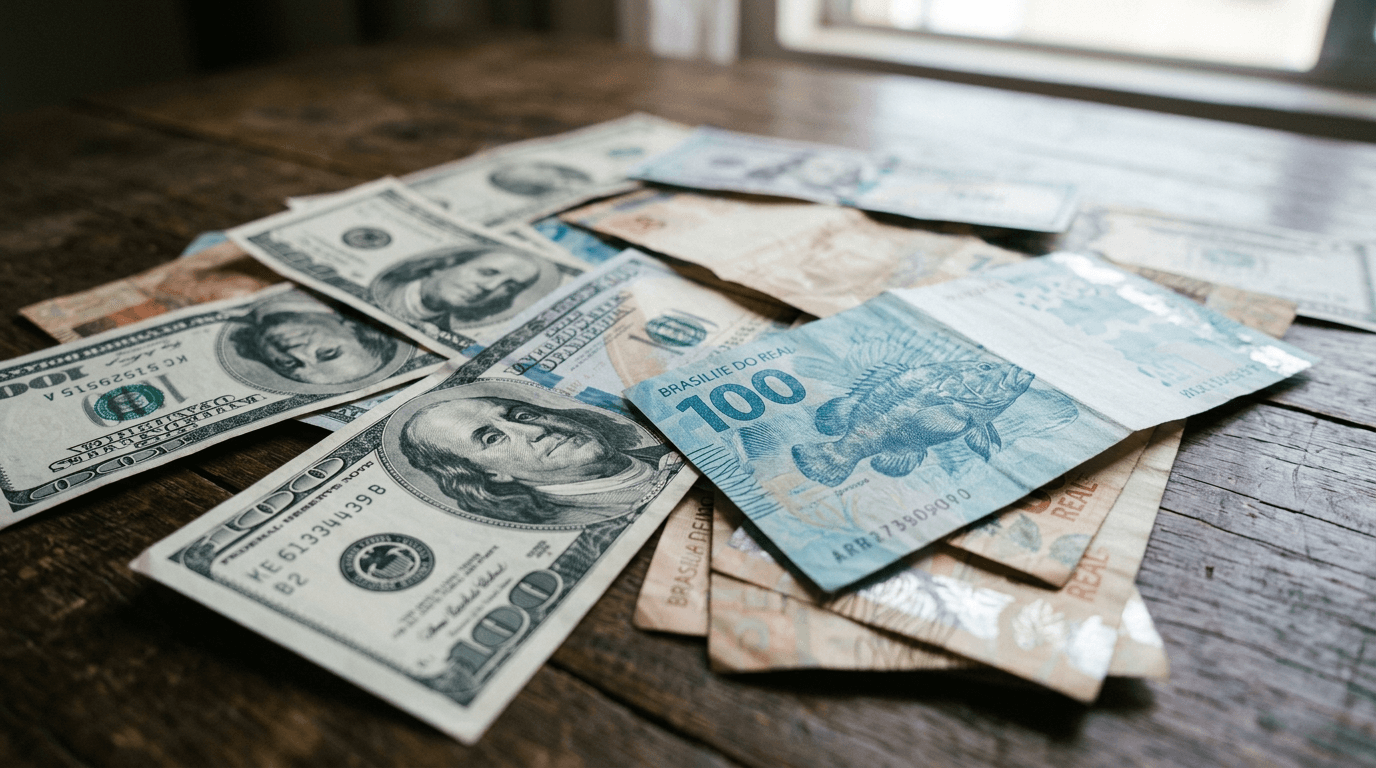
American retail investors holding cash in high-yield money market funds or short-term U.S. Treasuries are currently accustomed to earning a reliable yield. As of October 25, 2026, the Federal Reserve maintains its federal funds target range upper limit at 4.0%. While this domestic rate anchors the U.S. fixed-income market, a massive yield premium is quietly shifting capital flows across the Americas, altering the value of international funds that many retail investors already hold in their portfolios.
Just across the equator, Brazil's central bank, the Banco Central do Brasil, maintains its benchmark Selic rate at a staggering 13.75%, according to the SGS series 432 database. This leaves an immense interest rate gap of 9.75 percentage points between the two nations, a spread that has held completely flat compared to 30 days ago. For global macro traders, this rate gap is the lifeblood of the "carry trade"—a strategy where investors borrow in low-yielding currencies like the dollar to buy high-yielding assets denominated in the Brazilian real.
This wide yield cushion acts as a protective buffer for the Brazilian currency. When the gap is wide, it attracts foreign capital, supporting the brazil real vs dollar exchange rate. However, this high yield is not a free lunch; it reflects the deep political and fiscal risks that foreign investors demand to be compensated for. Brazil's monetary policy committee, known locally as Copom, has been gradually cutting the Selic rate from its previous peak of 15.0% in an effort to support economic growth, even as inflation expectations remain slightly unanchored.
For an American investor, tracking this yield gap is crucial because it directly influences the performance of broad Latin American equity funds. When the premium narrows—either because the Fed raises rates or Brazil cuts too quickly—foreign capital often flees Brazil, causing the real to depreciate and dragging down the dollar-denominated returns of Brazilian stocks. Conversely, a stable 9.75-point gap provides a strong incentive for institutional cash to stay parked in Brazilian debt, stabilizing local equity valuations.
In your brokerage app
If you hold the iShares MSCI Brazil ETF, a prominent exchange-traded fund listed in New York that tracks large and mid-sized Brazilian equities, your investment is highly sensitive to this interest rate differential. A wide rate gap supports the underlying currency, the brazil real, which boosts the fund's net asset value in U.S. dollar terms, whereas any sudden narrowing of the spread can trigger currency depreciation and drag down the fund's performance.