
Natura &Co Profit Plunges 92% on Derivatives Costs and Weak Brazil Performance
Brazilian cosmetics giant Natura &Co reported a 92.1% drop in Q2 2026 net income, driven by derivatives losses and operational struggles in its home market.
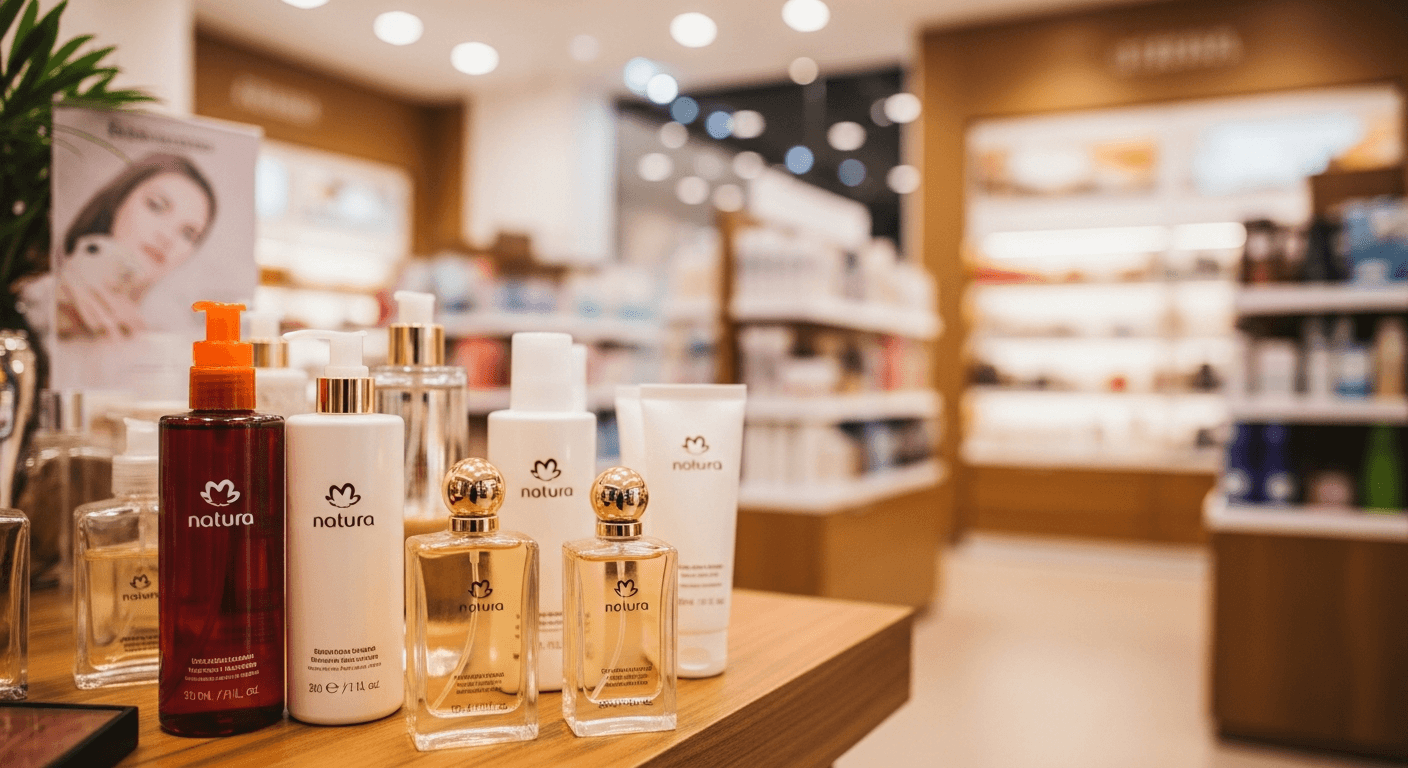
Brazilian cosmetics powerhouse Natura &Co (NATU3) posted a second-quarter 2026 net income of only R$35 million, marking a massive 92.1% decline from the same period last year on a recurring basis. The sharp profit drop, which fell significantly short of market consensus, signals deep short-term volatility and execution risk for the consumer giant as it navigates a challenging domestic environment and complex financial instruments.
The principal mechanism behind the earnings miss was a deterioration in the company's net financial result, largely attributed to costs related to the liquidation of derivatives and the impact of currency effects. For a company like Natura, which has operations across Latin America and manufactures internationally, managing currency exposure is critical, and these costs absorbed a significant portion of what would have been operating profit.
Beyond the financial headwinds, Natura &Co’s performance was hampered by persistent issues in its home market. Net revenue for the period fell 9.1% year-on-year to R$5.17 billion, a decline the company attributed to three primary factors in Brazil: product unavailability caused by internal operational adjustments, the generally adverse macroeconomic scenario marked by subdued consumer spending, and a temporary tax mismatch, specifically citing consumption tax changes in the state of São Paulo. The combination of these commercial and operational setbacks in its largest market complicated the company's efforts to offset the significant financial losses.
In contrast, the company’s operations in Hispanic markets, including Mexico and Argentina, showed resilience, posting accelerated constant-currency growth. This split performance—growth abroad against weakness at home—suggests the problems are concentrated on execution and market conditions in Brazil rather than a fundamental failure of the brand portfolio. To address the domestic drag, Natura &Co has already begun implementing measures to reconfigure its supply chain, adjust sales force models, and accelerate the expansion of digital sales channels.
The immediate next step for investors is to watch how quickly these operational adjustments translate into an improved top line. The company's ability to restore supply chain stability and navigate the full impact of the tax mismatch will determine whether the second half of 2026 can reverse the trend of revenue and profitability declines in its key market.
What it touches: Natura &Co’s shares, traded on the B3 exchange under the ticker NATU3, are sensitive to the health of the Brazilian consumer and the volatility of the Brazilian Real (BRL) against the US Dollar. The profit drop highlights how a consumer-facing company with significant international exposure can be hit by a confluence of domestic operational issues and currency-related financial maneuvers.