
Marcopolo’s Dominant ‘Caminho da Escola’ Win Underpins Volume Visibility Through 2027
Bus manufacturer Marcopolo (POMO4) secured the bulk of Brazil’s national school bus contracts, ensuring revenue visibility and reinforcing its value thesis.
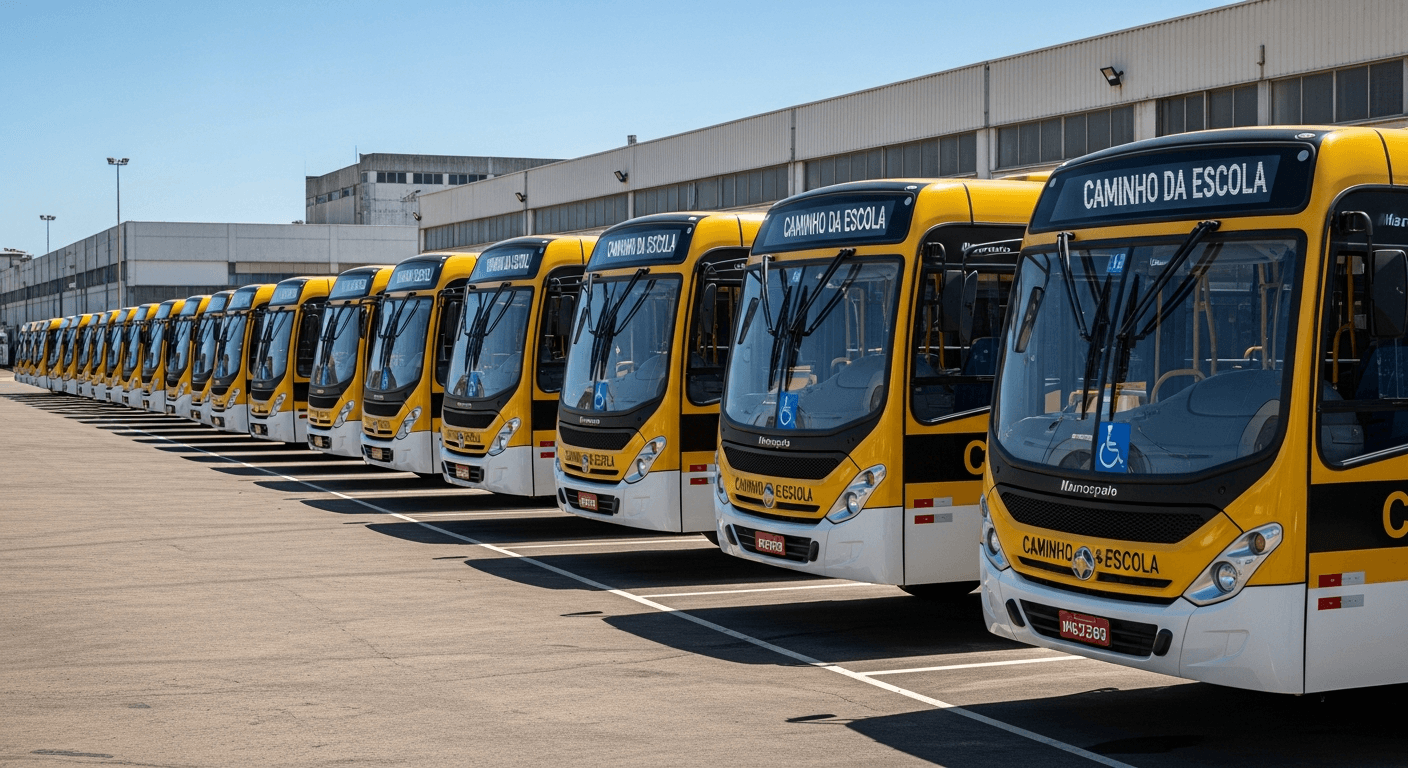
Marcopolo S.A. (POMO4), one of Brazil’s largest bus manufacturers, has cemented its near-term volume and revenue outlook after securing approximately 97% of the total units in the federal government’s latest “Caminho da Escola” school bus tender. The contract, which may encompass up to 7,400 units, provides the small-cap stock with production visibility that analysts believe will sustain robust factory utilization and revenue generation through 2027. The volume secured in the tender—a vital government program aimed at renewing the national school transport fleet—significantly exceeded analyst expectations, strengthening the investment case for Marcopolo, which is currently cited for its attractive valuation.
The large-scale victory in the 2026 tender reinforces Marcopolo’s operational planning amidst a domestic market that has faced uncertain demand in other segments. The total revenue from the new tender is projected to generate up to R$2.1 billion, representing an estimated 10% of the company’s projected top line for 2026 and 2027. The contract mechanism includes supplying its own micro-buses under the Volare brand and providing the bus bodies (carrocerias) for the chassis won by partner Volkswagen Caminhões e Ônibus, ensuring Marcopolo captures value across multiple lots. This substantial order volume locks in a base level of activity, a critical factor for industrial companies on the B3 exchange.
The company’s valuation metrics remain highly favorable, placing the stock firmly in value territory for Brazilian equities. Marcopolo is trading at a trailing twelve months (TTM) Price-to-Earnings (P/E) ratio in the range of 5.4x to 5.7x, which is significantly below the industry average and confirms the "around 6x projected earnings" thesis favored by analysts tracking the name. Furthermore, the stock offers a high dividend profile, with the reported TTM dividend yield reaching as high as 19.53%, although forward-looking analyst estimates for the yield are currently cited closer to 9%. The high yield, combined with the low earnings multiple, suggests the market has not yet fully priced in the earnings stability provided by the new government orders.
For investors, the next material step to watch is the official finalization and homologation of the tender results, which typically occurs within 30 days of the auction's conclusion. Final approval will allow the government to begin issuing purchase orders, which will dictate the precise delivery schedule and revenue recognition timeline over the next two years. In the broader market context today, the Ibovespa fell 1.52% to 174,041.95, with major stocks like Petrobras (PETR4) and Itaú Unibanco (ITUB4) down 1.72% and 1.08%, respectively, underscoring the importance of company-specific, de-risked revenue streams like the "Caminho da Escola" contract.