
Marcopolo (POMO4) Secures R$2.1 Billion 'School Path' Contracts, Boosting Revenue Visibility Through 2027
Bus manufacturer Marcopolo (POMO4) locks in R$2.1 billion in 'Caminho da Escola' contracts, significantly improving revenue visibility and stability.
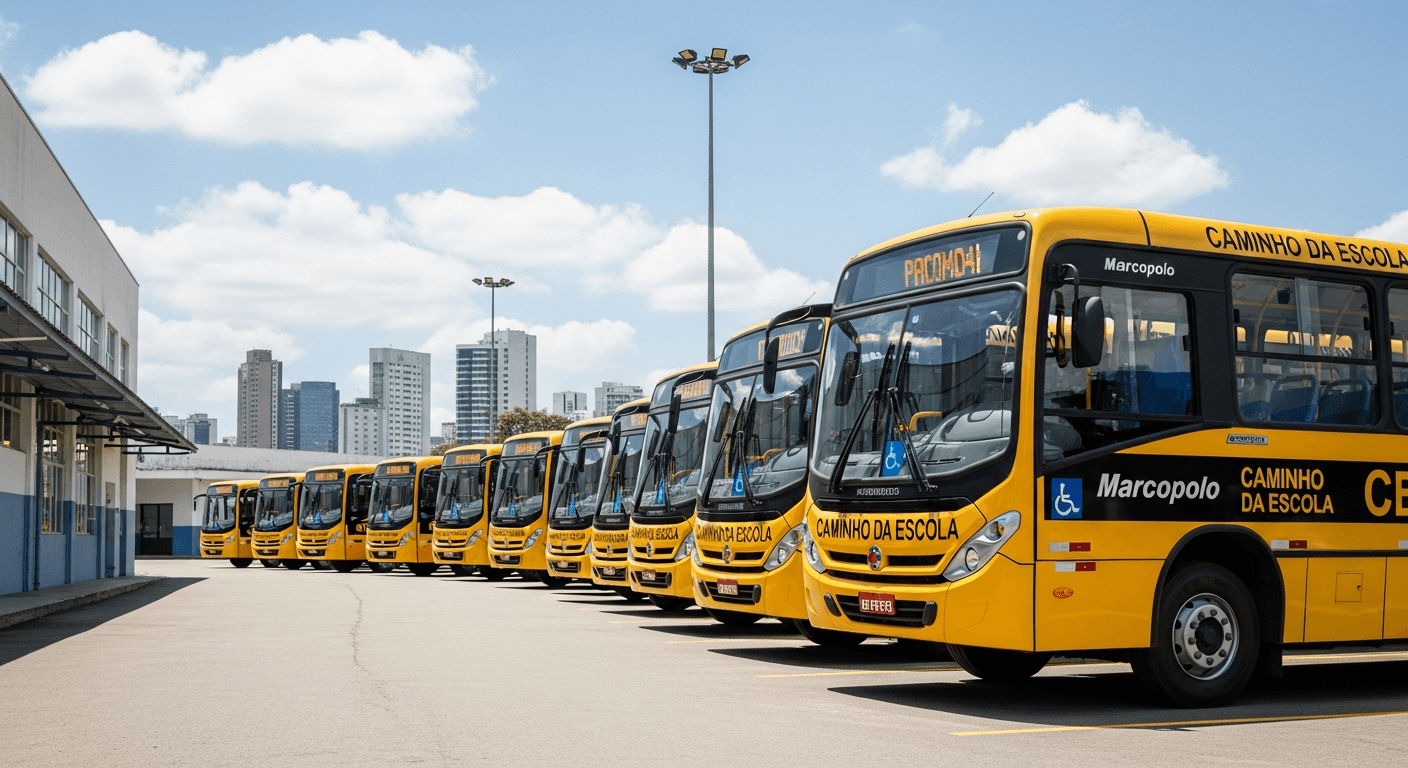
Marcopolo S.A. (POMO4) preference shares traded near R$5.32 on the B3, gaining market attention following the massive volume secured under the federal "Caminho da Escola" (School Path) program. While the broader Ibovespa (IBOV) index saw gains of 1.88% today, closing at 177,158.86, the bus manufacturer's stock has seen dramatically improved revenue visibility and predictability through 2027, driven by the new government contracts.
The central mechanism driving this attention is the massive order volume secured in the April 2026 tender for the "Caminho da Escola" program, a federal initiative to renew the public school transportation fleet. Marcopolo was awarded approximately 97% of the total contracts, representing a volume of up to 7,400 buses. This haul surpassed market expectations by a significant margin and is roughly 50% larger than the program’s historical average. According to estimates from financial institutions such as JP Morgan, the contract volume is expected to inject up to R$2.1 billion into Marcopolo's top line over the delivery period.
For investors tracking the B3 stocks, particularly in the Small Caps index (SMLL), this revenue boost acts as a powerful derisking factor for Marcopolo's operations. Analysts project that the "Caminho da Escola" orders could represent up to 10% of Marcopolo's projected net revenue for the 2026-2027 period. Furthermore, the contract pricing was favorable, with the average price per bus reaching approximately R$530,000, which is about 15% above the previous program's average. This blend of high volume, better pricing, and the stability of a major government client supports the company's long-term financial stability.
Moving forward, the primary factor for investors to monitor is the execution and delivery schedule of the "Caminho da Escola" orders, which are expected to be distributed over the next 24 months, concluding by early 2028. The next material data point for Marcopolo will be the company’s second-quarter 2026 earnings report, where management commentary on initial execution and margin capture from the new contract volume will be key to understanding the full financial impact.