
Regulatory Void in Brazil’s ReData Tax Program Freezes Pricing of Data Center Debt
Institutional investors are delaying risk assessment on infrastructure debentures for data centers until the Brazilian government finalizes key regulations for the newly approved ReData tax incentive regime.
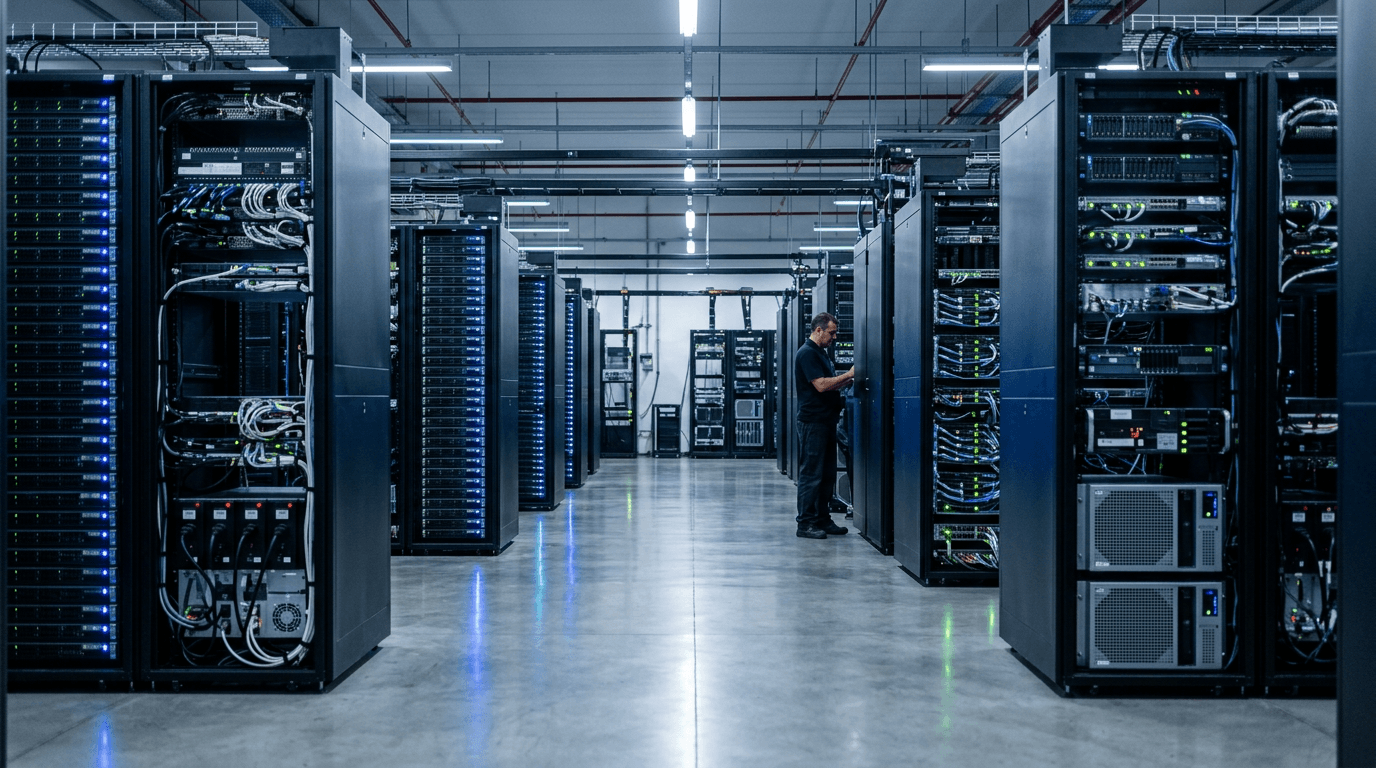
Institutional investors are holding off on fully pricing the risk of infrastructure debt linked to Brazil’s growing data center sector, despite the recent sanctioning of a major federal tax incentive law designed to spur investment. The government has approved the Special Tax Regime for Data Center Services, known as ReData (Law No. 15,504/2026), but the lack of key implementing regulations is preventing the accurate valuation of these financing instruments, keeping a significant portion of capital on the sidelines.
The new law, signed on September 15, aims to position Brazil as a major hub for digital infrastructure by offering a five-year suspension of federal taxes—including the Import Tax and IPI—on the purchase of Information and Communication Technology (ICT) equipment used in data center construction. The move is critical to satisfying the country's high latent demand: government estimates show that roughly 60% of Brazil’s digital workloads are currently processed on data centers located abroad, representing a massive domestic investment opportunity for cloud computing, AI, and hyperscale operations.
However, the incentives are conditioned on compliance with strict environmental criteria that still lack regulatory definition. The biggest point of uncertainty centers on energy: the law requires participating data centers to meet their electricity demand with sources that are “renewable or low-emission,” but the specific technical criteria defining what qualifies as "low-emission" have yet to be published by the Federal Executive Branch. Furthermore, the final list of specific equipment eligible for the tax suspension—which directly impacts a project's capital expenditure (CAPEX)—is also pending a definitive government act.
For institutional investors, this regulatory gap translates directly into unquantifiable risk. Without a final definition of eligible equipment, the ultimate cost of a new facility remains uncertain, complicating financial modeling. More crucially, the ambiguity over "low-emission" energy means compliance—a prerequisite for the tax benefit—cannot be fully guaranteed, forcing financiers to wait before they can accurately assess the security of tax-incentivized infrastructure debentures. The next step to watch is the publication of these final regulations, which will be essential for unlocking the investment required to bring a substantial share of those 60% of offshore digital workloads back into Brazil.
What it touches
The continued regulatory uncertainty primarily impacts the capital expenditure and financing costs for data center developers and operators. As a result, the repricing of risk for infrastructure debentures—a key financing instrument for major projects in Brazil—will remain on hold until the Ministry of Finance issues the missing regulatory acts.
Related coverage
Politics · PRO
Top Senator Proposes Legislation Targeting 'Predatory Pricing' by Foreign Firms in Brazil
Published
Politics · PRO
Political Uncertainty in Brazil Election Threatens R$6.7 Billion Amazon Fund and EU Agribusiness Access
Published
Politics · PRO
Polarization Deepens as Brazil’s Top Presidential Candidates Face Near-Identical 55% Rejection Rates
Published