Brazil Delays Sin Tax to February 2027, Easing Beverage and Auto Hit
Brazil's Finance Ministry has postponed the start of its new "sin tax" to February 2027, maintaining current industrial tax rates through a transitional agreement.
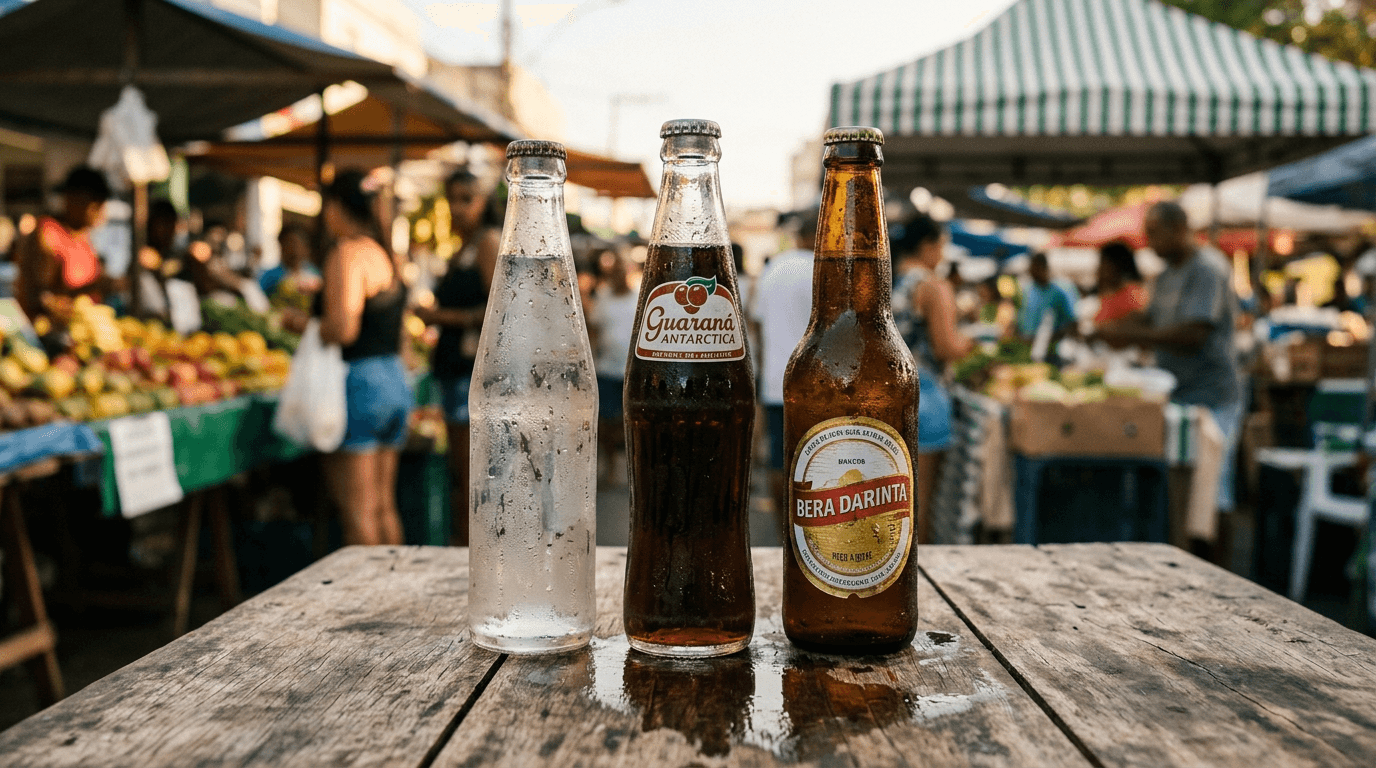
Global beverage and automotive conglomerates operating in Latin America’s largest economy have secured a temporary reprieve from a major tax overhaul. On November 3, 2026, Brazil's Finance Ministry announced it is sending a provisional measure to Congress to establish the tax rates for its highly anticipated "sin tax" (Imposto Seletivo). However, due to a constitutional grace period, the official collection date has been pushed back from January 1 to February 1, 2027.
The delay is a direct consequence of Brazil's strict constitutional "noventena" rule. This fiscal mechanism mandates that a minimum of 90 days must elapse between the official publication of a new tax rate and its actual collection. Because the executive branch did not finalize the rates until November 3, 2026, the government was legally barred from collecting the tax on the original start date of January 1, 2027.
To prevent an immediate price shock for consumers and protect corporate planning, the Finance Ministry, led by Executive Secretary Dario Durigan, negotiated directly with major industrial lobbies. Under the newly brokered agreement, the government will extend the existing Industrialized Products Tax (IPI) through January 2027. When the new selective tax takes effect in February, the initial tax burden will remain equivalent to the old IPI rates. This parity is scheduled to remain locked in place until the end of 2027, giving companies a stable transition period.
The Imposto Seletivo was created under Brazil's historic consumption tax reform to discourage the consumption of goods deemed harmful to human health or the environment. The levy will target alcoholic beverages, sugary drinks, tobacco, vehicles, and mineral extraction. While the tax is ultimately designed to rise over time, the government's decision to maintain tax parity through 2027 shields corporate planning from sudden regulatory shocks.