
Brazilian Lithium Miner Sigma Falls 4.15% on NASDAQ Despite Production Beat
Sigma Lithium stock dropped following Q2 earnings release as production wins were overshadowed by profit and valuation concerns.
Sigma Lithium Corporation, the Brazilian miner whose shares are one of the few Brazilian equities US investors can buy directly without using an American Depositary Receipt (ADR), saw its stock fall 4.15% to close at $11.33 on Friday. The sharp drop came immediately following the release of the company’s second-quarter earnings report, signaling investors’ deepening concern that operational successes are not translating quickly enough into the financial performance required to justify its premium valuation.
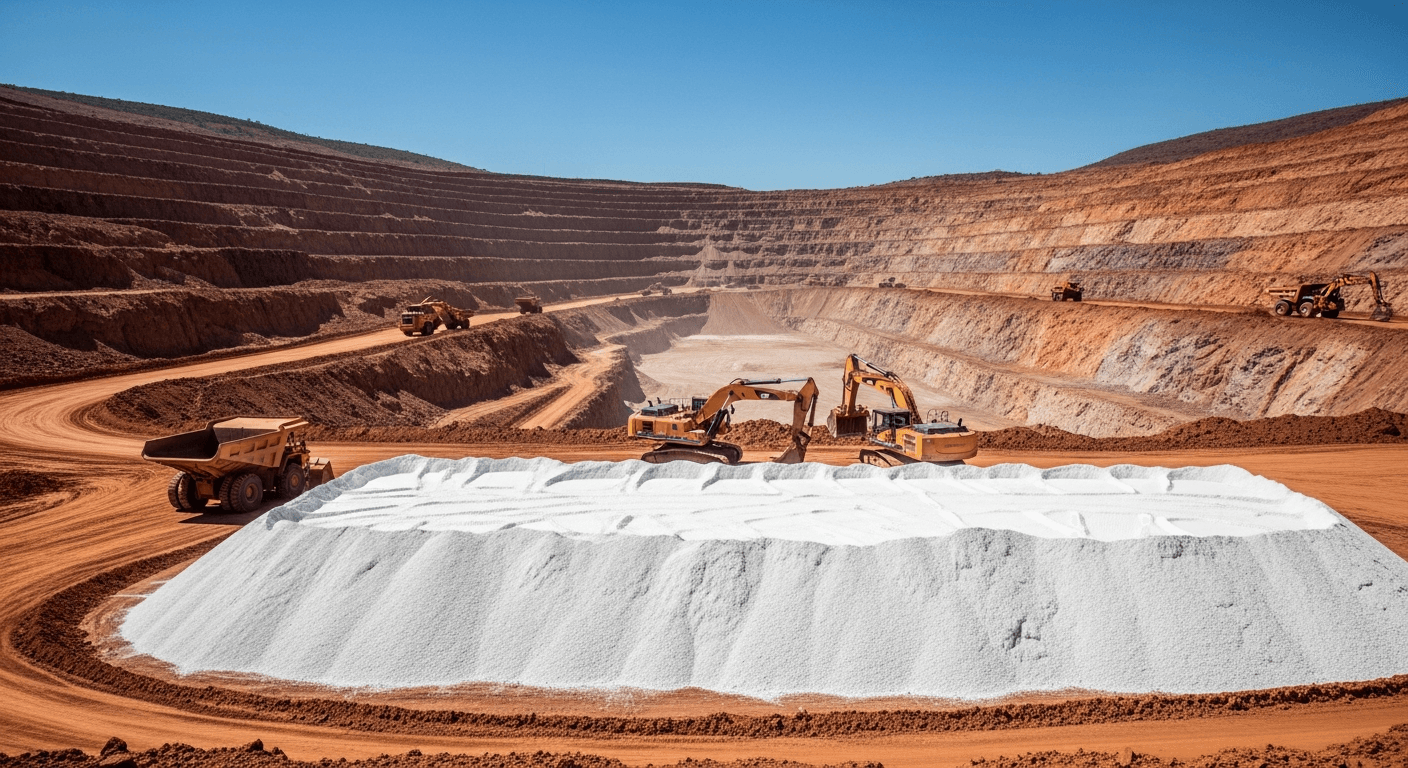
Sigma Lithium operates the Grota do Cirilo complex in the Vale do Jequitinhonha region of Minas Gerais, where it produces lithium concentrate—a key component for electric vehicle (EV) batteries. As the largest producer of lithium oxide concentrate in the Americas, the company's performance is closely watched by investors seeking exposure to Brazil's role in the global EV supply chain. Its unique primary listing on the NASDAQ makes it a bellwether for how US retail investors view the long-term prospects of this segment of the Brazilian economy.
The market reaction highlights a fundamental tension in the company’s story. Ahead of the earnings release, Sigma had already announced strong operational results for the quarter, reporting that it exceeded its production guidance by 6%, delivering 35,000 tonnes of high-grade lithium concentrate. This confirmed the company’s ability to execute a planned mining upgrade successfully. However, the market’s focus remains on the financial bottom line. Analysts have pointed to the company’s ongoing unprofitability and a high price-to-sales ratio, suggesting its valuation is based on aggressive expectations for future lithium prices and sales growth that its Q2 results failed to confirm.
The negative sentiment also reflects the persistent weakness in the global lithium market. Despite Sigma’s operational efficiency and its focus on environmentally and socially sustainable practices, the company’s top line remains highly sensitive to a broader structural surplus that continues to cap the price for the material. The failure of the Q2 report to alleviate concerns about the path to profitability, even with a strong production beat, appears to have prompted the selling pressure.
Moving forward, investors will be watching for progress on the company's Phase 2 expansion at Grota do Cirilo, which aims to double annual production capacity to 520,000 tonnes. For the stock to recover, management will need to show that this increased scale can be achieved on schedule and that it will dramatically lower unit costs, finally allowing revenue gains to outpace expenses and push the firm toward sustained profitability.
What it touches The decline in Sigma Lithium Corporation (SGML) shares exposes investors in the global lithium and electric vehicle supply chains to the reality that strong operational execution in Brazil’s mining sector does not immediately offset broader global commodity price weakness and market skepticism over growth valuations.