
Brazilian Vehicle Financing Hits 15-Year High Despite High Interest Rates
Brazilian vehicle financing volume reached 683,928 units in August 2026, the highest for the month in 15 years, signaling surprising credit resilience.
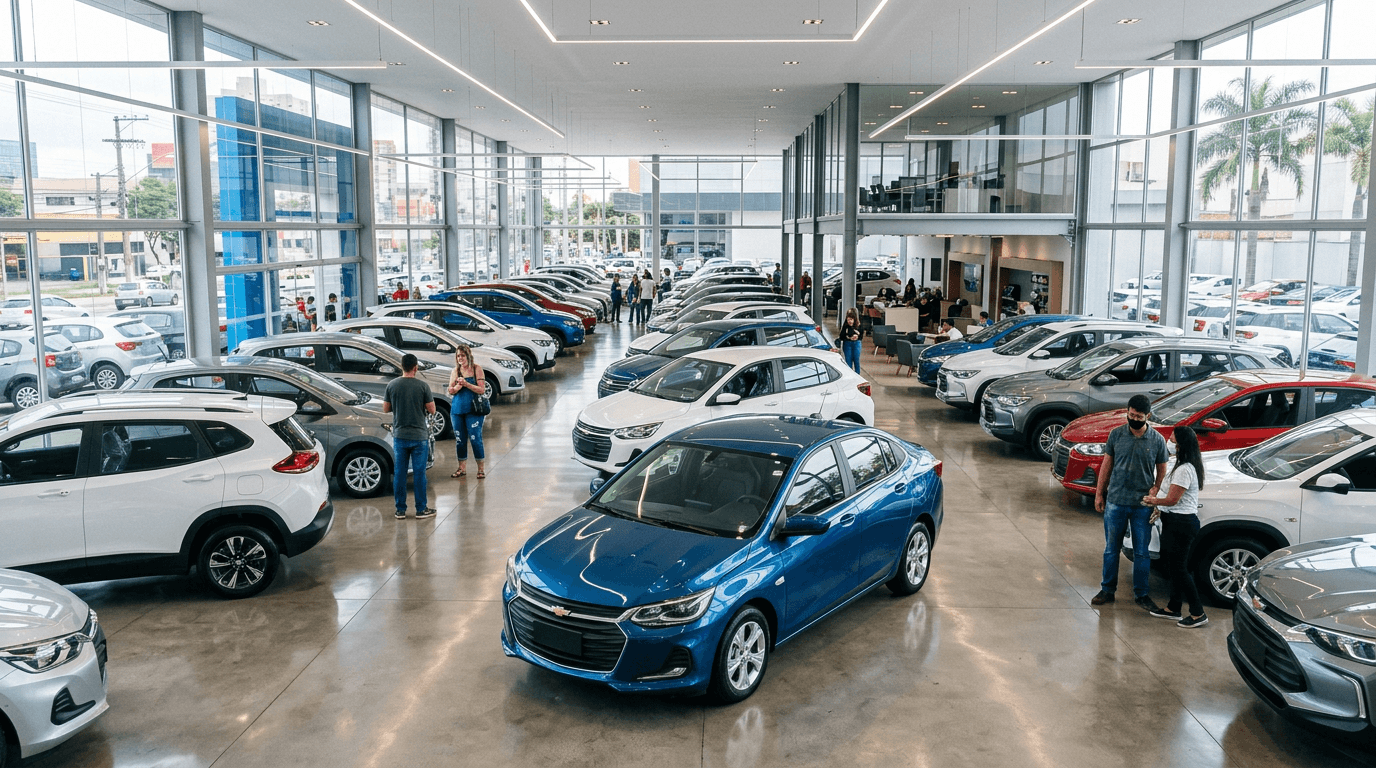
Vehicle financing in Brazil reached a 15-year high for the month of August, with consumers financing 683,928 units in August 2026. The figure, a notable 10.4% increase from August 2025, signals a surprising resilience in consumer credit demand despite the country's persistently high-interest rate environment.
The data comes from Trillia, the data intelligence arm of B3, which is the Brazilian stock exchange. For the intelligent foreign reader, this context is key: the benchmark Selic rate, set by the Central Bank of Brazil, was 14.00% in August, representing one of the highest real interest rates in the world. This high cost of capital is intended to restrict borrowing and curb inflation, making the surge in vehicle credit a remarkable economic indicator.
The consistent high volume points to robust consumer confidence and a market adapting to expensive credit. Thiago Gaspar, the Superintendent of Client Relations at Trillia, specifically noted that the sustained growth “shows the resilience of the market even in moments of volatility in the economy and high interest rates.” This is consistent with a market where manufacturers and lenders are aggressively expanding auto loan offerings and facing intensified price competition.
Light vehicles accounted for the majority of the total volume, with 478,000 units financed in August. This segment, which includes passenger cars and light commercial vehicles, is the main driver of the overall growth, suggesting that everyday Brazilians are prioritizing vehicle ownership despite the high cost of financing a depreciating asset.
The Central Bank has recently cut the Selic rate to 13.75%, which remains a historically high level, but the August financing figures indicate that credit demand has a momentum of its own. The primary question for the Brazilian economy is whether this consumer confidence and credit demand can be sustained, or if the high rates will eventually dampen the appetite for long-term financing.
What it touches
The sustained growth in vehicle financing has direct implications for sectors tied to consumer credit and discretionary spending. The resilience of this credit market is a positive sign for Financials—specifically banks and financial institutions that originate vehicle loans—and for the Consumer Discretionary sector, which includes auto manufacturers and dealerships operating in Brazil. The movement points to strong underlying demand in the domestic credit market.